Business
Not The Right Time To Impose New Taxes , Oyedele Warns Governments

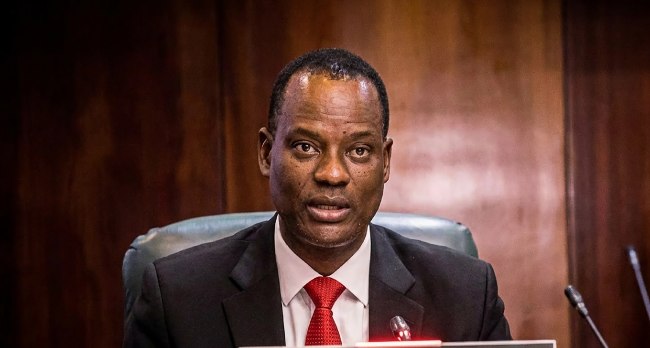
Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, has cautioned governments against introducing new taxes or increasing existing tax burdens on vulnerable citizens and productive sectors, warning that such measures could deepen economic hardship.
Oyedele spoke on the sidelines of the 2026 annual meetings of the International Monetary Fund (IMF) and World Bank in Bangkok, Thailand, where he presented a communiqué on behalf of the Intergovernmental Group of Twenty-Four (G24), which he chairs.
“This is the wrong time to impose new taxes or increase the burden of tax, particularly on the vulnerable population and productive sectors of the economy,” he said.
Responding to questions on how developing countries could reduce debt-servicing costs without cutting essential public spending,report quoted Oyedele as urging governments to identify waste, find savings and improve revenue collection before placing additional financial pressure on citizens and businesses.
He said borrowing remained necessary to finance economic growth but stressed that governments must ensure that debt supports job creation and inclusive development.
“Borrowing and debt financing is a necessary condition for growth, and every country emerging, developing must be able to apply debt financing in a way that is overall of positive impact, particularly to stimulate job-rich and inclusive growth,” he said.
The minister also called for available public funds to be prioritised for essential services, including healthcare and education, while private capital could help finance other areas of investment.
On the choice between taxation and borrowing, Oyedele said both options carried consequences and should be considered in the context of their impact on household welfare.
“If you collect taxes, you raise the money now, and that itself has a lot of trade-offs. What taxes are you collecting? You collect taxes from the most vulnerable, and this will deprive them of money to provide food, health, education,” he said.
He argued that excessive taxation could leave low-income households with less money for basic needs, while borrowing also carried future obligations.
“Debt is future taxes, so it’s not one or the other. It’s to strike a balance, bearing in mind ultimately that the essence of tax and of debts is to cater for the people,” Oyedele said.in the report.
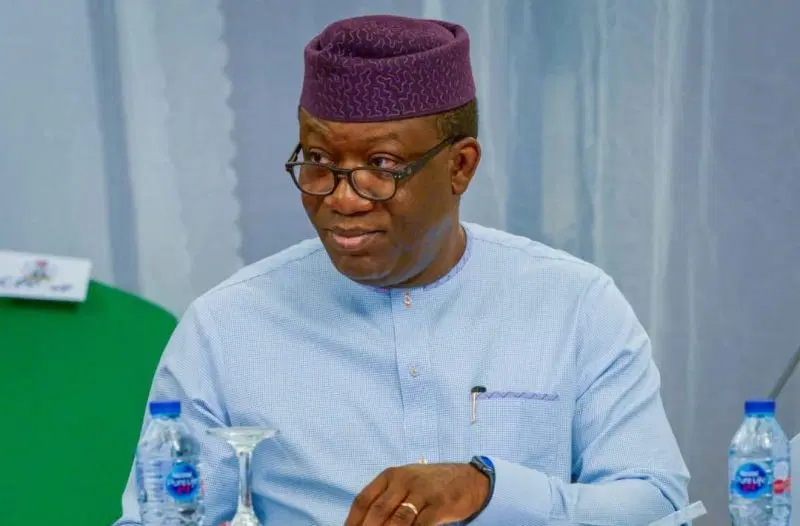
Former Governor of Ekiti State and ex-Minister of Mines and Steel Development, Dr Kayode Fayemi, has warned the United States against slipping into isolationism in its engagement with Africa, insisting that Nigeria remains a must-have strategic partner in the evolving global order.
Fayemi maintained this position in Lagos while speaking as a panelist at the Nigeria Moment, a Nigeria–United States Strategic Dialogue organised by the American Business Council in collaboration with the Heritage Foundation.
In his presentation, which focused on why Nigeria is a must-have partner in the changing world order, Fayemi,former chairman of the Nigeria Governors’ Forum (NGF) stressed the need for a more holistic relationship between both countries grounded in transparency, mutual benefit and shared prosperity.
He insisted that Nigeria must be treated as a strategic partner in the emerging world order.
“While welcoming the growing American interest in Nigeria’s vast mineral endowment, Fayemi warned that the partnership must go beyond resource extraction.
“Nigeria must be engaged as a strategic actor and a co-creator in shaping the future of global energy and resource governance, rather than as a testing ground for experiments. A partnership built on mutual respect, shared interests and long-term cooperation offers the strongest foundation for an enduring relationship between Nigeria and the United States,” Fayemi said.
Describing the engagement as a pleasure, Fayemi said the dialogue brought together a distinguished group of policymakers, business leaders and strategic thinkers to reflect on the future of Nigeria-US relations.
He commended the convener of the dialogue, Mr Ayo Otuyalo,for an excellent convening and for bringing together such high-level participants for the important strategic conversation.
The conference featured Governor Babajide Sanwo-Olu of Lagos State as keynote speaker, alongside senior representatives of the Federal Government, including the Minister of Industry, Trade and Investment, Dr Jumoke Oduwole; Minister of Power,
Also st the event were : Engr Joseph Tegbe; Minister of Solid Minerals Development, Mr Dele Alake, represented by Engr Simon Nkom; and the Head of the Nigerian Upstream Petroleum Regulatory Commission (NUPRC), Mrs Oritsemeyinwa Eyesan among others.
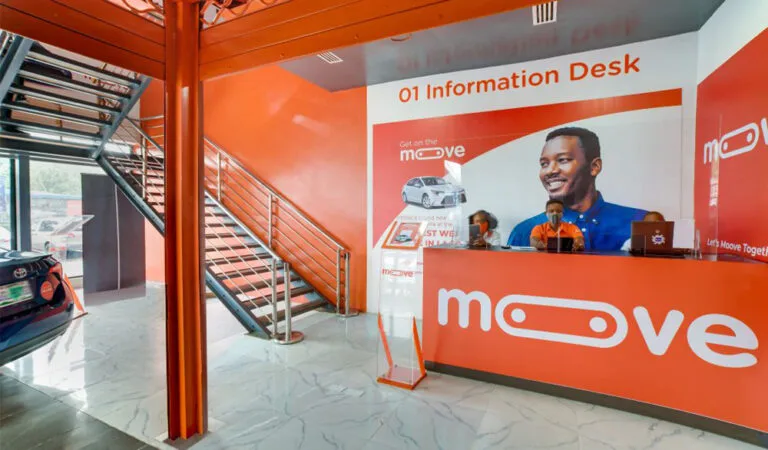
Moove, the global mobility company founded in Lagos, has announced plans to end its operations in Nigeria.
According to report, as part of its exit strategy, the company founded six years ago, said it will transfer full ownership of eligible vehicles “worth approximately N35 billion” to existing customers at no cost.
The affected customers will take full ownership of the vehicles, with no further payments to Moove required from October 1, 2026.
The company said the move forms part of its plans to conclude its Nigerian operations while ensuring that eligible customers retain the vehicles they have been using under its financing model.
Moove was founded by Ladi Delano and Jide Odunsi and has built its business around providing vehicle financing and mobility solutions to drivers.
The company launched in Nigeria six years ago and expanded its operations by financing vehicles for drivers, particularly those operating on ride-hailing platforms.
The report says the transfer of the vehicles means eligible customers will receive assets collectively valued at about N35 billion without making additional payments to the company.
Moove is a global mobility fintech company that has expanded its operations across several markets, providing vehicle financing and other mobility-related services.
This is coming a few weeks after another global mobility company Uber exited Nigerian operations, the report concluded.
The federal government says late tax payments will attract new interest rates from October 1, 2026.
According to a statement by the ministry of finance, the new rates are linked to market interest rates and will be set for each calendar month.
Under the order, interest on tax payable in naira will be charged at the Central Bank of Nigeria (CBN’s) monetary policy rate (MPR) plus one percentage point, compared with the previous five-percentage-point spread.
However, the ministry said the rate would not fall below the yield on 364-day treasury bills.
This means that since the MPR is 23 percent, taxpayers who pay late would be charged 24 percent interest on the delayed tax, subject to the 364-day treasury bill yield floor.
For tax payable in foreign currency, the statement said the interest rate will be the secured overnight financing rate (SOFR) plus 6 percentage points. The SOFR stands at 22.12 percent for the 30-day average and 22.59 percent for the 90-day average as of September 24, 2026.
The ministry said the new rates would provide taxpayers with greater certainty over the cost of late payment, which it said has been linked more closely to prevailing market rates.
Speaking on the move, Taiwo Oyedele, minister of finance and coordinating minister of the economy, said the new framework would ensure that delaying tax payments does not become a cheaper source of credit than borrowing from the market.
“Tax that is due belongs to the public. When it is paid late, Government may have to borrow to fill the gap, and the cost falls on everyone,” Oyedele said.
“This Order ties the cost of late payment to real market rates, so that delaying tax does not become a cheaper form of credit than the market itself.”
The ministry said under the order, one interest rate would apply for each calendar month and would be determined on the last business day of the preceding month.
“The Nigeria Revenue Service (NRS) is required to publish the applicable rate on its website by the third business day of every month,” the statement added.
The ministry said interest would be calculated as simple interest on a daily basis, from the date the tax becomes due until payment is made.
For foreign-currency tax, the ministry said SOFR would apply as the international benchmark for US dollar rates, noting that if the SOFR is discontinued, its official successor rate would apply.
Oyedele said the arrangement would also provide a uniform basis for taxpayers dealing with federal, state and FCT tax authorities.
“Just as important is certainty. Every taxpayer, whether dealing with the Nigeria Revenue Service or a State revenue service, will know the rate in advance, see it published every month, and be charged in the same way,” he said.
“Clear rules make compliance easier and support a fair, predictable tax system.”
The ministry said the order does not change the 10 percent penalty for late payment provided under section 65 of the Nigeria Tax Administration Act (NTAA), 2025.
“The relevant tax authorities may also waive interest or penalties where good cause is shown, in line with section 66 of the Act,” it said.
The ministry said the new rates would apply to interest arising from October 1, including interest on tax that became due before that date.
“Interest that arose before October 1 will not be affected to the extent that it was specifically provided for under the rules in force at the time,” the statement said.
The finance ministry said the order supersedes the 2017 notice on interest on unpaid taxes and other earlier notices on the subject.
The ministry said the framework applies to self-assessment taxpayers, the NRS, and state and Federal Capital Territory (FCT) internal revenue services.
The ministry advised taxpayers to file their returns and pay applicable taxes on time.
It also advised taxpayers with outstanding liabilities to settle them promptly or engage the relevant tax authority.
-
 Health & Wellness1 year ago
President Tinubu Directs Cut in Dialysis Cost from ₦50,000 to ₦12,000
-
News2 years ago
CBN Debunks Fake Circular on New ₦5,000 and ₦10,000 Notes
-
 International News7 months ago
Indian Police Arrest Nigerian Over ₦290m Drug Haul
-
 Business7 months ago
Dangote Refinery Reduces Petrol Gantry Price To ₦1,200 Per Litre
-
 Business7 months ago
After Plea Bargain, Court Discharges Stella Oduah of ₦2.5bn Fraud
-
Business2 years ago
Dangote; We Did Not Fix ₦600/Litre Petrol Price
-
 Trending News1 year ago
NELFUND Disburses ₦86bn To 449,000 Beneficiaries
-
 Opinion2 years ago
Championing the People’s Voice: Obasa’s Dedication to Grassroots Representation By Dave Agboola⁰