Business
Personal Finance – ABC of Investing – FBNQuest Asset Management

Whether your dreams include buying a home, starting a business, or traveling the world, sound financial management is the key to turning these dreams into reality. Personal finance is the comprehensive practice of managing your money in a way that aligns with your financial aspirations and goals. This multifaceted discipline includes a variety of activities such as budgeting, saving, investing, and planning for retirement. Each of these components plays a crucial role in ensuring your financial stability and growth.
Budgeting in personal finance is the process of creating a plan to manage your income, expenses, and savings. It involves deciding in advance how you will allocate your money to cover various needs and goals. Here are some key points about budgeting, Income and Expenses, Spending Control, Savings. Creating a budget can give you more control over your finances and help you achieve both short-term and long-term financial stability. Do you have any specific goals or areas you’d like to focus on in your budget?
Savings refers to the portion of your income that you set aside and do not spend immediately. This money is typically reserved for future use, such as emergencies, large purchases, or long-term goals like buying a house or retirement. cash idling in a savings account becomes wasteful because it loses purchasing power to inflation over time. Instead, cash not tied up in an emergency should be placed in something that will help it maintain its value or grow, such as investments.
Investing is the act of allocating money into financial assets or ventures with the expectation of generating a profit or income over time. Investing can be a powerful tool for growing your wealth, but it’s important to understand the risks and do thorough research or consult with a financial advisor.
Planning for retirement in personal finance involves preparing financially for the period in your life when you will no longer be working full-time. The goal is to ensure you have enough money saved and invested to maintain your desired lifestyle after you stop working. It’s never too early to start planning and seeking advice from a financial advisor can be very helpful.
Keep in mind that managing personal finances is an ongoing journey, not a single destination. The financial landscape is always evolving, and it’s crucial to stay informed and adaptable. Continuously educating yourself about new financial strategies and adapting to changing circumstances will help you navigate this journey successfully. By doing so, you can ensure that your financial decisions are well-informed and aligned with your long-term goals.
Here are few steps to aid your journey into sound personal finance management.
Access your Financial Health
Financial health refers to the overall condition of your financial situation, encompassing all actions that impact your monetary affairs. It’s important to recognize that everyone’s circumstances are unique, so it’s essential to tailor your assessment to your personal needs and goals. Financial health includes various aspects, such as:
Cash Balance: A growing cash balance indicates positive financial health.
Expenses and Debt: Monitor your expenses and debt, such as credit cards, mortgages, and loans. Aim for minimal fluctuations in expenses.
Savings and Net Worth: Assess your net worth—whether it’s positive or negative. Consider your savings, investments, and assets available for current or future use.
Investment Returns: Strong returns on investments contribute to financial health. Diversify your investments for stability.
To improve your financial health:
Assess your net worth Pay down your debts
Create a budget you can stick to Build an emergency fund
Understanding Investment basics
An investment involves using capital in the present to increase an asset’s value over time. It’s the act of allocating resources (usually money) with the expectation of generating income, profit, or gains. When making an investment decision, an individual must consider some key factors; investment objective, risk and return, liquidity need and investment duration.
Investment Objective
An investment objective is a set of financial goals that guide an investor’s decisions regarding their investment. The objective of the investment defines the goal of an investment. It could be Increasing the value of your investment over time (Growth), generating regular income from the investment (Income), Protecting the initial investment from loss or a combination of more than one. Understanding your investment objective helps in creating a tailored investment strategy that aligns with your personal finance goal.
Risk and Returns
In personal finance, risk refers to the potential for losing some or all your investment. When considering risk, it’s important to understand both your willingness and ability to take take risks. These two concepts help determine your overall risk tolerance.
Willingness to Take Risk
This is your personal comfort level with taking risks. It reflects your attitude and emotional response to potential losses and gains.
Some people are naturally more risk-averse, preferring safer investments, while others are more risk-tolerant and comfortable with the possibility of higher losses for the chance of higher returns.

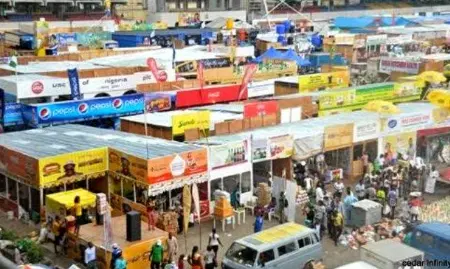
The Lagos International Trade Fair Complex Management Board (LITFCMB) has condemned the use of its facility for the production of counterfeit products and other illegal activities, pledging to work with regulatory and law enforcement agencies to rid the complex of such practice
The board also commended the National Agency for Food and Drug Administration and Control (NAFDAC) for its recent enforcement operation, which led to the arrest of two persons allegedly linked to the illegal revalidation of expired drinks and the production of counterfeit consumables within the complex.
In a statement issued on Wednesday, the Executive Director and Chief Executive Officer of LITFCMB, Veronica Safiya Ndanusa, said the activities were contrary to the board’s commitment to promoting legitimate trade and ethical business practices.
She disclosed that relevant authorities had commenced investigations to establish the facts surrounding the incident and identify measures to prevent a recurrence.
Ndanusa warned that individuals and businesses found culpable of engaging in activities that endanger public health or undermine the integrity of local manufacturing would face the full weight of the law.
“As a body rooted in the principles of ethical business practices, transparency and genuine trade, we strongly condemn any activity that threatens public safety or brings the reputation of the Lagos International Trade Fair Complex Management Board into disrepute,” she said.
“Our facility exists to provide a conducive environment for legitimate businesses to thrive, not to serve as a breeding ground for the production or distribution of counterfeit and substandard products.”
The board chief assured members of the public that the management would collaborate with relevant regulatory and law enforcement agencies to ensure that the complex remained free of illegal activities.
She also urged traders and business operators within the facility to comply with established standards, stressing that the pursuit of profit must never come at the expense of consumers’ health and safety.
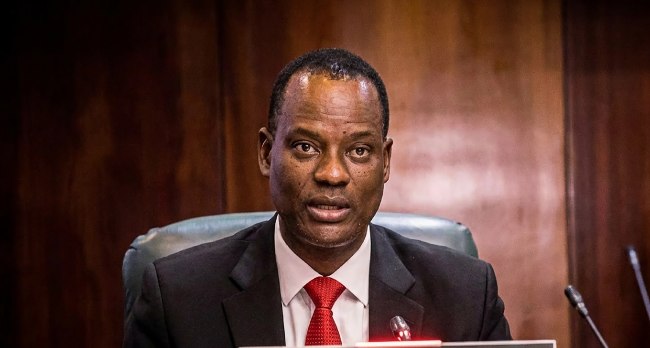
Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, has cautioned governments against introducing new taxes or increasing existing tax burdens on vulnerable citizens and productive sectors, warning that such measures could deepen economic hardship.
Oyedele spoke on the sidelines of the 2026 annual meetings of the International Monetary Fund (IMF) and World Bank in Bangkok, Thailand, where he presented a communiqué on behalf of the Intergovernmental Group of Twenty-Four (G24), which he chairs.
“This is the wrong time to impose new taxes or increase the burden of tax, particularly on the vulnerable population and productive sectors of the economy,” he said.
Responding to questions on how developing countries could reduce debt-servicing costs without cutting essential public spending,report quoted Oyedele as urging governments to identify waste, find savings and improve revenue collection before placing additional financial pressure on citizens and businesses.
He said borrowing remained necessary to finance economic growth but stressed that governments must ensure that debt supports job creation and inclusive development.
“Borrowing and debt financing is a necessary condition for growth, and every country emerging, developing must be able to apply debt financing in a way that is overall of positive impact, particularly to stimulate job-rich and inclusive growth,” he said.
The minister also called for available public funds to be prioritised for essential services, including healthcare and education, while private capital could help finance other areas of investment.
On the choice between taxation and borrowing, Oyedele said both options carried consequences and should be considered in the context of their impact on household welfare.
“If you collect taxes, you raise the money now, and that itself has a lot of trade-offs. What taxes are you collecting? You collect taxes from the most vulnerable, and this will deprive them of money to provide food, health, education,” he said.
He argued that excessive taxation could leave low-income households with less money for basic needs, while borrowing also carried future obligations.
“Debt is future taxes, so it’s not one or the other. It’s to strike a balance, bearing in mind ultimately that the essence of tax and of debts is to cater for the people,” Oyedele said.in the report.
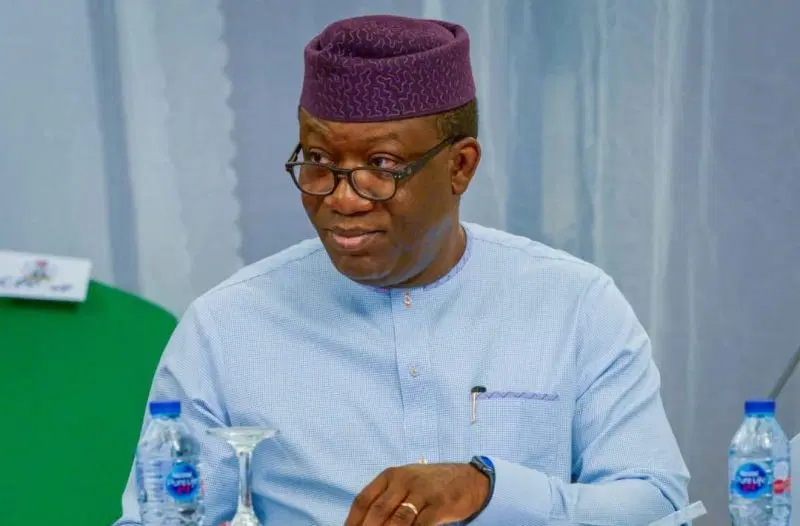
Former Governor of Ekiti State and ex-Minister of Mines and Steel Development, Dr Kayode Fayemi, has warned the United States against slipping into isolationism in its engagement with Africa, insisting that Nigeria remains a must-have strategic partner in the evolving global order.
Fayemi maintained this position in Lagos while speaking as a panelist at the Nigeria Moment, a Nigeria–United States Strategic Dialogue organised by the American Business Council in collaboration with the Heritage Foundation.
In his presentation, which focused on why Nigeria is a must-have partner in the changing world order, Fayemi,former chairman of the Nigeria Governors’ Forum (NGF) stressed the need for a more holistic relationship between both countries grounded in transparency, mutual benefit and shared prosperity.
He insisted that Nigeria must be treated as a strategic partner in the emerging world order.
“While welcoming the growing American interest in Nigeria’s vast mineral endowment, Fayemi warned that the partnership must go beyond resource extraction.
“Nigeria must be engaged as a strategic actor and a co-creator in shaping the future of global energy and resource governance, rather than as a testing ground for experiments. A partnership built on mutual respect, shared interests and long-term cooperation offers the strongest foundation for an enduring relationship between Nigeria and the United States,” Fayemi said.
Describing the engagement as a pleasure, Fayemi said the dialogue brought together a distinguished group of policymakers, business leaders and strategic thinkers to reflect on the future of Nigeria-US relations.
He commended the convener of the dialogue, Mr Ayo Otuyalo,for an excellent convening and for bringing together such high-level participants for the important strategic conversation.
The conference featured Governor Babajide Sanwo-Olu of Lagos State as keynote speaker, alongside senior representatives of the Federal Government, including the Minister of Industry, Trade and Investment, Dr Jumoke Oduwole; Minister of Power,
Also st the event were : Engr Joseph Tegbe; Minister of Solid Minerals Development, Mr Dele Alake, represented by Engr Simon Nkom; and the Head of the Nigerian Upstream Petroleum Regulatory Commission (NUPRC), Mrs Oritsemeyinwa Eyesan among others.
-
 Health & Wellness1 year ago
President Tinubu Directs Cut in Dialysis Cost from ₦50,000 to ₦12,000
-
News2 years ago
CBN Debunks Fake Circular on New ₦5,000 and ₦10,000 Notes
-
 Business7 months ago
Dangote Refinery Reduces Petrol Gantry Price To ₦1,200 Per Litre
-
 International News7 months ago
Indian Police Arrest Nigerian Over ₦290m Drug Haul
-
 Business7 months ago
After Plea Bargain, Court Discharges Stella Oduah of ₦2.5bn Fraud
-
Business2 years ago
Dangote; We Did Not Fix ₦600/Litre Petrol Price
-
 Trending News1 year ago
NELFUND Disburses ₦86bn To 449,000 Beneficiaries
-
 Opinion2 years ago
Championing the People’s Voice: Obasa’s Dedication to Grassroots Representation By Dave Agboola⁰